Current Ripper withdrawal terms at a glance
| Item | Current published position | Source recheck | How to interpret it |
|---|---|---|---|
| Withdrawal methods | Bitcoin, eZeeWallet, bank transfer | 9 September 2026 | These are the routes marked for withdrawals on the current official banking page. |
| Listed withdrawal time | 2 days for Bitcoin, eZeeWallet and bank transfer | 9 September 2026 | A platform processing label, not a guaranteed end-to-end arrival time. |
| Weekly withdrawal limit | Up to $2,000 per customer per week | 9 September 2026 | A balance above that figure should not be assumed to leave the account in a single week. |
| Bank-transfer withdrawal fee | $50 | 9 September 2026 | Applies to the current bank-transfer listing; recheck before submitting a cashout. |
| Verification | Required for withdrawals | 9 September 2026 | Identity, address and payment ownership can be reviewed before payment. |
| Exact KYC processing time | Not verified | 9 September 2026 | This guide does not invent a fixed verification turnaround. |
The three verified withdrawal routes
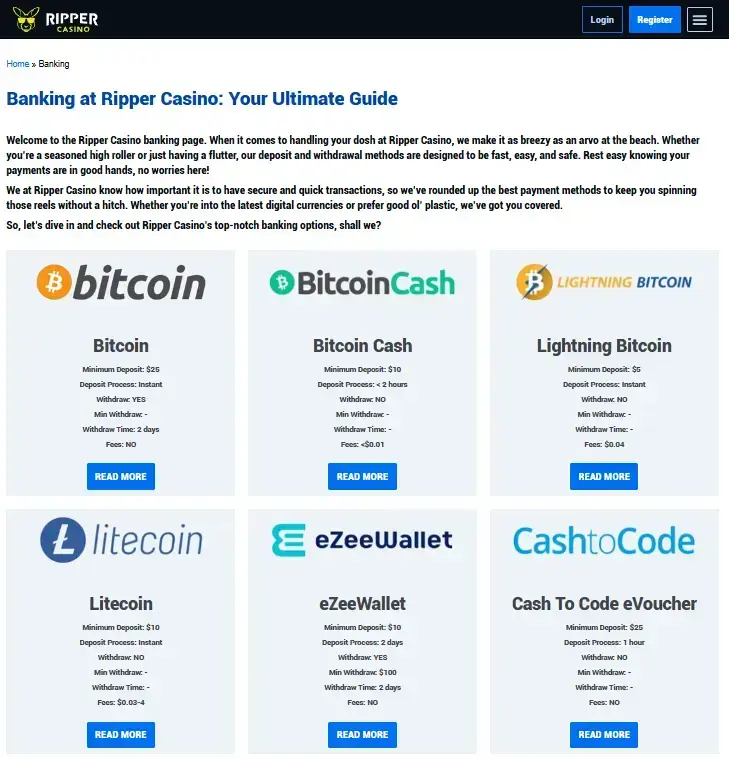
The current withdrawal set is much narrower than Ripper’s deposit menu. That distinction is important. Ripper lists many ways to fund an account, but the banking page currently marks only Bitcoin, eZeeWallet and bank transfer for withdrawals. A deposit method should never be assumed to support the return journey simply because it appears in the cashier.
Bitcoin
Bitcoin is the only named cryptocurrency in the current banking table that is explicitly marked for withdrawals. The page lists a 2-day withdrawal time. That is the casino’s published processing figure. It does not cover every external factor that can affect when a user sees spendable funds, and it should not be converted into a promise of a fixed settlement time.
eZeeWallet
eZeeWallet is also marked for withdrawals, again with a 2-day listed time. It is one of the few methods that appears on both the deposit and withdrawal sides of the current cashier structure. Even so, account verification still applies, so a wallet route does not bypass identity or payment-ownership checks.
Bank transfer
Bank transfer is the traditional cashout option in the current set. The banking page lists a 2-day withdrawal time and a $50 fee. Because that fee is material, a bank-transfer cashout should be assessed on the current live terms rather than treated as a generic no-fee bank payment. The value is freshness-sensitive, so it belongs in a page that is rechecked before publication rather than in a static site-wide promise.
For the wider directional map of funding and cashout rails, use the Ripper Casino payments overview. It explains why deposit convenience and withdrawal convenience need to be assessed separately.
What the 2-day payout label actually means
A listed withdrawal time is best understood as a platform term, not as a stopwatch that starts when the user clicks withdraw and ends only when the money is fully available elsewhere. The current official banking page lists 2 days for Bitcoin, eZeeWallet and bank transfer. The figure is useful because it sets the operator’s published processing expectation, but it should not be stretched beyond what the source says.
Several stages can sit around the payment event. Ripper requires verification for withdrawals, including identity, address and payment-method details. Those checks are logically separate from the simple method-level timing label on the banking page.
This distinction also explains why user-reported experience is a different evidence class from a published processing table. Current independent review sources were checked during page preparation, but individual cashout stories are treated as anecdotes rather than transaction-level proof. A decision should therefore give more weight to current primary terms for method, limit and fee values, while treating review stories as context rather than as a substitute for account records.
The weekly limit: up to ,000 per customer
Ripper’s current terms state a maximum withdrawal of up to $2,000 per customer per week. The wording matters. A balance above that published weekly ceiling should not be assumed to be available for withdrawal in one weekly period.
A user comparing a potential balance with the weekly limit should think in scheduling terms rather than assuming that the full balance can leave the account at once. The practical issue is not only the size of a single request. It is how the published weekly ceiling interacts with any larger balance, verification review and the selected withdrawal route.
The limit should also be kept separate from bonus-specific cashout restrictions. Certain promotional offers can have their own wagering or maximum-withdrawal rules. Those rules are not the same thing as the general weekly withdrawal limit. If the balance includes promotional funds, read the deposit options record together with the bonus terms that applied when the deposit or offer was used, rather than assuming that one limit replaces every other condition.
KYC can be part of the cashout review
Ripper requires account verification for withdrawals. The current terms say users must provide valid proof of identity, address and payment-method details. The responsible-gaming page specifically says payment requests are not processed without verification that includes a recent utility bill and valid government ID in the same name as the player.
Those requirements make consistency important. Registration details, identity documents and the ownership of the payment method should line up. The useful preparation point is to keep the identity, address and payment-method information supplied for verification accurate and internally consistent.
This page deliberately does not publish an exact KYC processing time because no current official turnaround is verified in current sources. It also does not turn a general verification requirement into a claim that every user will be asked for the same additional document set. The dedicated Ripper verification guide handles document-level KYC questions without expanding this withdrawal page into a full account-verification manual.
Bonus terms and cashout planning
If a balance is connected to a promotion, treat the promotion conditions as a separate cashout check rather than assuming that the general withdrawal table answers every eligibility question. Bonus wagering and promotion-specific cashout rules belong to the offer itself, while the 2-day method labels and the weekly withdrawal limit belong to the current banking and general terms.
This page does not restate every bonus condition because doing so would duplicate the dedicated bonus coverage and increase the risk of mixing terms from different offers. The practical step is to identify whether a promotion is active and read the conditions attached to that offer before submitting a withdrawal.
That separation also prevents an individual dispute from being assigned an invented cause. A delayed or rejected request can involve different account-level questions, and an external review does not provide the complete account record. This guide therefore uses the current official withdrawal and verification facts as its primary evidence and leaves individual complaint analysis to the reputation page.
Plan the cashout path before a large balance builds
The most useful time to understand a withdrawal policy is before the account balance becomes large relative to the published weekly ceiling. With a current limit of up to $2,000 per customer per week, a larger balance can require more than one weekly payout period under the published terms. That does not predict how a specific account will be handled, but it does make the limit relevant to planning rather than something to discover only after a win.
Method choice matters at the same stage. Bank transfer currently carries a $50 listed withdrawal fee. This guide does not turn one fee value into a recommendation because method choice has other practical considerations. The point is to compare the current fee information, the route you control, the account-verification status and the amount you expect to withdraw before choosing a cashout method.
A clean withdrawal record also helps if support is needed later. Keep the request amount, submission date, selected route and any verification request together. That creates a factual timeline and makes it easier to distinguish a payment-processing question from a document-review or bonus-compliance question.
A practical withdrawal checklist
- Check the live withdrawal menu. Confirm that Bitcoin, eZeeWallet or bank transfer is actually displayed for the account at the time of the request.
- Recheck the current limit and fee. The published weekly ceiling and bank-transfer fee are dynamic terms, so use the current cashier and terms rather than an old review reference image.
- Confirm account details match. The name on the account, identity evidence and controlled payment route should be consistent.
- Finish the required verification. Ripper requires verification for withdrawals.
- Check promotion status. Do not assume a bonus-linked balance is immediately withdrawable before the relevant wagering conditions are complete.
- Keep records. Save the withdrawal request, method, amount, time submitted and any support correspondence so that a later timing discussion is based on an actual transaction trail.
- Separate platform time from total arrival time. The 2-day figure is the current published withdrawal time for the three listed methods, not a guaranteed universal outcome.
How to read withdrawal complaints responsibly
Cashout complaints are decision-useful because withdrawal friction is one of the highest-impact issues a casino user can face. They are still evidence of individual experiences, not controlled tests. A single positive review cannot establish guaranteed payout reliability, and a single negative review cannot establish a systematic refusal to pay.
The more useful approach is to compare the complaint theme with primary rules. If a review mentions verification, check whether verification is actually required. It is. If a review mentions a weekly limit, check the current terms. They currently state up to $2,000 per customer per week. If a review refers to a particular fee or timeframe, compare it with the latest official banking page rather than assuming the review is current.
The site keeps that evidence hierarchy separate on purpose. For a fuller treatment of review distributions, complaint themes and support response signals, use the Ripper reputation page. This withdrawal guide stays focused on the mechanics that can be verified directly.
Bottom line
Ripper’s current published cashout structure is relatively clear but restrictive enough to require planning. Bitcoin, eZeeWallet and bank transfer are the verified withdrawal routes. All three currently carry a 2-day listed withdrawal time, bank transfer carries a $50 listed fee, and the current terms state a maximum withdrawal of up to $2,000 per customer per week.
The most important qualifier is not a vague warning. It is the documented verification layer. Withdrawals are subject to audit, identity and address evidence are required, and payment ownership matters. Bonus compliance can also determine whether a balance is eligible to be withdrawn. Treat those steps as part of the cashout workflow, keep transaction records, and avoid interpreting a method-level time label as a guaranteed end-to-end payout promise.
For the broader brand assessment, return to the Ripper Casino Australia review.