Current Ripper deposit methods
| Method | Type | Current role | Best comparison question |
|---|---|---|---|
| PayID | Account-to-account addressing service | Deposit | Is PayID visible in your current cashier and are the recipient details correct? |
| Visa | Card | Deposit | Does your issuer permit the transaction? |
| Mastercard | Card | Deposit | Does your issuer permit the transaction? |
| Neosurf | Prepaid voucher | Deposit | Do you prefer funding without using your main card directly? |
| CashToCode | Voucher-style funding | Deposit | Does prepaid budgeting suit the amount you plan to use? |
| eZeeWallet | E-wallet | Deposit | Do you prefer a wallet-based funding route? |
| JetBank | Bank-style transfer | Deposit | Is the method available for your account session? |
| Bitcoin | Cryptocurrency | Deposit | Is a crypto funding workflow already familiar to you? |
| Bitcoin Cash, Lightning Bitcoin, Litecoin, Ether, Tether | Cryptocurrency | Deposit | Which asset and network do you already understand and control? |
PayID: the most Australian-specific deposit option
PayID is the strongest local-context method in Ripper’s current deposit list. It is a mainstream Australian payment rail, and the RBA’s 2025 survey found that around 80% of respondents knew about PayID and around 50% had used it in the previous year. That usage rate rose from 32% in the 2022 survey.
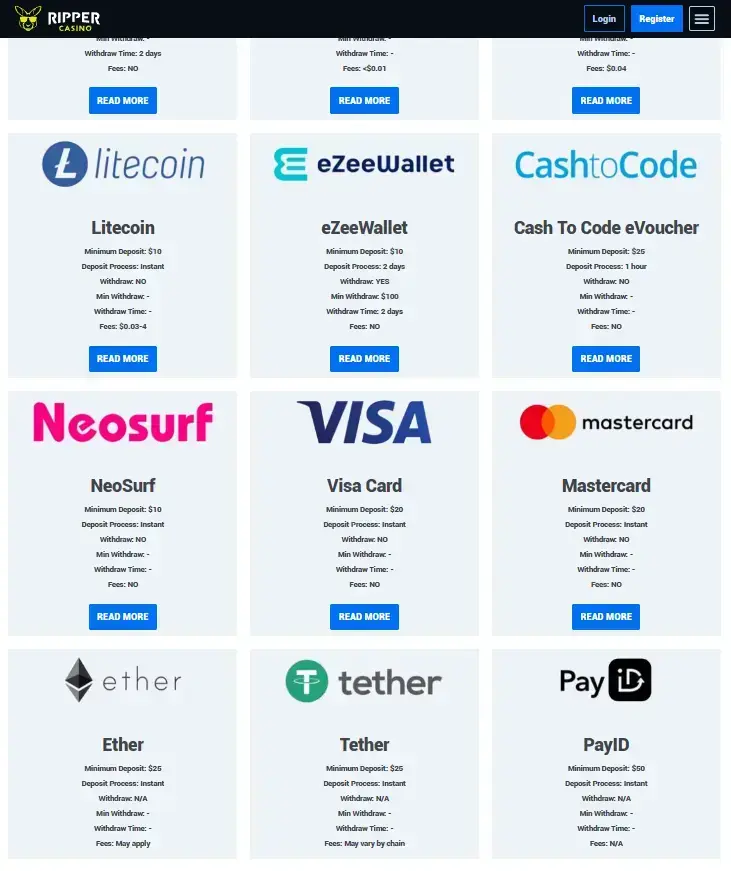
Ripper’s current banking page lists PayID as a deposit option and currently shows a $50 minimum deposit. That minimum is a freshness-sensitive value, so it should be checked again in the cashier before a payment is made. The page also labels the deposit process as instant, but this guide does not translate that label into a guaranteed end-to-end crediting time. A payment can still depend on the sending institution, payment routing and the casino account session.
The national adoption figures explain why PayID is relevant to an Australian-facing deposit guide. They should not be turned into a claim that every Australian bank permits payments to an offshore casino. Bank policy remains a separate layer, and method availability at Ripper is not the same fact as bank approval.
Cards: familiar payment behaviour, separate issuer rules
Visa and Mastercard are listed as deposit methods on the current Ripper banking page. Cards also remain the most widely used consumer payment method in Australia. The RBA’s 2025 survey found that cards accounted for most consumer payments and continued to dominate both in-person and online transaction behaviour.
That makes cards familiar, but familiarity is not the same as universal compatibility. An Australian card issuer can apply its own rules to gambling merchants, international transactions, cash-like transactions or particular merchant categories. The defensible statement is that Ripper lists Visa and Mastercard for deposits. A stronger statement such as “all Australian cards work” would go beyond the evidence.
Before using a card, check the amount shown in the cashier, confirm any issuer-side fee or block, and keep a record of the transaction. If a deposit is declined, repeated retries can make troubleshooting harder. It is usually more useful to identify the reason than to cycle through the same card details.
Neosurf and CashToCode: prepaid funding for a defined budget
Neosurf and CashToCode are useful because they behave differently from a directly linked bank card. They are prepaid or voucher-style routes, so the amount available through the instrument is defined before the casino deposit is made. That can make them easier to fit into a fixed entertainment budget.
The trade-off is that a deposit-only voucher is not a complete cashout strategy. Ripper’s current banking page does not identify Neosurf or CashToCode as withdrawal routes. A user who funds with a voucher should therefore check the separate withdrawal options before assuming money can return through the same channel.
This is one reason the broader Ripper Casino payments guide separates funding rails from cashout rails. A deposit method should be judged not only on how easy it is to load funds, but also on how it fits the account’s eventual withdrawal and verification path.
eZeeWallet: a wallet-based deposit route
eZeeWallet is currently listed among Ripper’s deposit methods. It gives the deposit menu a wallet-based option alongside cards, vouchers, PayID, JetBank and crypto. That matters for readers who already prefer to separate online payments from a primary card or direct bank workflow.
This deposits page does not use the wallet label to make a broader cashout promise. Ripper requires verification for withdrawals, and withdrawal rails are handled on the dedicated cashout page. The useful deposit-side question is simply whether a wallet workflow already fits the way you manage online payments.
If you already use an e-wallet, another wallet-based deposit route can be easier to understand than a new crypto or voucher process. If you do not use one, the method should be compared with PayID, cards and prepaid options rather than treated as automatically superior.
JetBank and bank-style deposits
JetBank appears in the current Ripper deposit list as another bank-style funding option. It should be treated as its own cashier rail rather than confused with the bank transfer method that the current page marks for withdrawals. The two labels serve different roles in the current banking structure.
For an Australian user, the useful check is whether JetBank appears for the specific account session and whether the transfer instructions match the details displayed in the cashier. Bank-based methods can be familiar, but they still sit inside the casino’s payment workflow rather than creating a general guarantee of bank approval.
If your main objective is to understand which route can later receive funds, move to the Ripper withdrawals guide. This deposits page deliberately avoids turning a bank-style funding option into an unsupported cashout claim.
Crypto deposits: multiple assets, niche Australian payment usage
Ripper currently lists Bitcoin, Bitcoin Cash, Lightning Bitcoin, Litecoin, Ether and Tether for deposits. This is a wider crypto set than a simple “Bitcoin accepted” label suggests. This page treats all six strictly as deposit options and leaves withdrawal-route analysis to the separate cashout guide.
Australian payment data provides useful scale. The RBA’s 2025 survey found that only around 2% of respondents had used cryptocurrency to make a payment in the previous year. Crypto awareness was much higher, but actual payment usage remained low compared with cards and PayID. Ripper crypto deposits are therefore a brand feature, not a mainstream Australian payment norm.
Crypto also adds a different decision path from PayID or cards. A reader should choose it because the digital-asset payment workflow is already familiar, not because the casino lists several crypto names. The important verified point here is availability: Ripper currently lists six named crypto deposit options, while Australian consumer-payment use of cryptocurrency remains low compared with PayID and cards.
Most importantly, crypto is not a legal or verification shortcut. It does not remove account rules, source-of-funds questions or withdrawal checks. Use it only if the payment mechanics are already familiar, not because it appears more detached from conventional banking.
How to compare the deposit methods by use case
- If local familiarity matters most
- PayID has the clearest Australian context and strong national adoption, but bank approval still needs to be treated separately.
- If you want a familiar everyday instrument
- Visa or Mastercard fit common Australian payment behaviour, subject to issuer rules.
- If you want a prepaid spending boundary
- Neosurf or CashToCode can separate the amount loaded from an open-ended card balance.
- If you already use an e-wallet
- eZeeWallet has the practical advantage of appearing in both the deposit and current withdrawal sets.
- If you already understand crypto
- Ripper provides several digital-asset deposit routes, but they add network and value considerations.
There is no single objectively “best” Ripper deposit method. The right comparison depends on which rail you already use, what your bank or issuer permits, how clearly you can document the payment and how the funding method connects to the eventual withdrawal path.
Deposit checks that reduce avoidable friction
- Confirm the method in the live cashier. Do not rely on an older image or review table.
- Check the current minimum. Method minimums can change and should be read from the cashier immediately before payment.
- Use payment details you control. Account ownership matters later when withdrawals and verification are reviewed.
- Record the transaction. Save a reference number or receipt in case the deposit needs to be traced.
- Do not infer a withdrawal route. Deposit-only methods should not be assumed to support cashouts.
- Read bonus conditions separately. If a promotion is attached to the deposit, the Ripper Casino bonuses guide explains why wagering terms can affect the usable balance.
Deposits, account setup and verification are connected
A deposit sits inside an account rather than functioning as an isolated payment. The account information used during setup should be kept consistent because Ripper requires verification for withdrawals. A straightforward deposit does not remove that later account-checking step.
If you are still at the setup stage, read the registration guide before choosing a funding rail. That makes it easier to understand how account details, payment ownership and later verification fit together without overloading the deposit step itself.
Bottom line
Ripper Casino’s current deposit menu is broad: PayID, Visa, Mastercard, Neosurf, CashToCode, eZeeWallet, JetBank and six named crypto options are all present on the official banking page. PayID has the strongest Australian-specific relevance, cards are the most familiar mainstream payment instrument, vouchers provide prepaid funding, eZeeWallet spans both deposits and withdrawals, and crypto serves a smaller group already comfortable with digital-asset transfers.
The useful choice is the method that you can verify, control and document, not simply the method described as fastest. Check the live cashier, check issuer or bank rules, and know the separate withdrawal route before funding the account. For the site-wide assessment, return to the Ripper Australia guide.